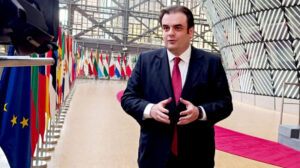
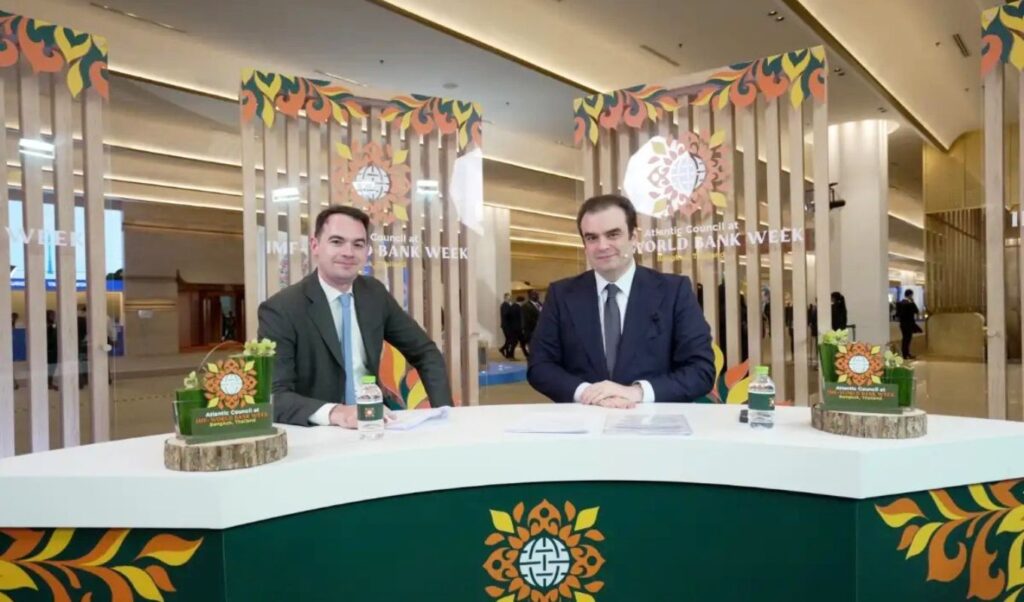
Eurogroup President Kyriakos Pierrakakis has stressed the need for consolidation of the European banking system, pointing out that the EU needs to create European “champions” in the banking sector, alongside smaller, specialized regional banks that respond to local community needs. Pierrakakis highlighted the growing difficulties stemming from the energy crisis, underscoring that the era of cheap and abundant financing is over. He also emphasized that banks must receive support while also contributing in return. Speaking at an event organized by the Atlantic Council focused on boosting productivity in Europe, Kyriakos Pierrakakis exchanged views with Charles Lichfield. During the discussion, he noted that “the era of cheap and abundant capital is a thing of the past,” adding that “modern markets are pricing risk at elevated levels.” As he explained, this outcome is the result of heightened inflationary expectations, geopolitical challenges, energy pressures, supply bottlenecks, global developments, and rising demand for investment in artificial intelligence. “All these factors, simultaneously, combined with a more challenging fiscal environment, are pushing bond yields higher,” he said.
Read also: Pierrakakis at the IMF: Europe withstands successive shocks — Georgieva praises Greece for early loan repayment
The case for larger banks
When asked whether a common deposit guarantee scheme should be established first, or whether regulations should be aligned before any common guarantee is introduced, the Eurogroup chief stated that, in any case, larger banks are needed to support citizens and businesses.
“We will look at the technical details, but in reality we all know what the end result should be. The end result should be bigger banks, of better quality, which will be able to compete at a global level. I would say that we certainly need European champions in the banking system, alongside smaller, specialized regional banks that will respond to the needs of local communities. We need a combination of both. Such a combination exists in the United States. So the question is: why shouldn’t we have it in Europe as well? I believe this is an entirely achievable reform, which, together with the reform of capital markets, will play an enormous role in how the European economy can grow further. Because, as I said, we have proven our resilience. Now we need to build on that resilience in order to achieve better outcomes for every European citizen,” he said.
Greece as a model
Kyriakos Pierrakakis was asked to comment on the current situation in the eurozone and whether there is any connection to the challenges Greece faced during its bailout program years. He noted that Greece’s trajectory changed when the country took ownership of its reform agenda and when the entire population came to understand the benefits of fiscal credibility.
He underlined that “fiscal credibility is national power,” adding that it is “essentially a strategic asset,” and pointed out that one only needs to compare today’s bond market landscape with that of 2016 to appreciate how dramatically the environment has changed. “The average yield on ten-year bonds back then, in 2016, was 1.1%. The average yield on ten-year bonds in Europe today is 4%. So this is a different environment, at a time when the fiscal situation is under greater pressure. Because the average fiscal deficit back then was 1.7%, while today it stands at 3.5% — it has more than doubled. Under these conditions, markets are watching the fiscal trajectory of countries very closely.”
Among other points, Kyriakos Pierrakakis noted that each country’s fundamentals are now different, given the new fiscal framework within which Europe operates today, the strengthening of institutional capacity that took place after the financial crisis, and the fact that “our banks are much better capitalized than they used to be” and “Europe is no longer where it once was.” However, he stressed that “we all need to be aware of the need to keep our public finances in order, because the credibility of national governments’ fiscal path plays a decisive role in how it is perceived and assessed by bond markets.”